आपकी salary अच्छी है, job stable है और आप loan के लिए apply करते हैं।
फिर भी bank आपकी income के साथ एक और चीज देख सकता है—आपने पहले लिया हुआ credit कितनी जिम्मेदारी से manage किया है।
यहीं Credit Score काम आता है।
India में लोग अक्सर हर Credit Score को “CIBIL Score” कहते हैं, जबकि दोनों technically एक ही चीज नहीं हैं। CIBIL एक credit bureau है, जबकि Credit Score broader term है।
इस article में इसी confusion को clear करते हुए समझेंगे कि score बनता कैसे है, किन habits से खराब हो सकता है और इसे धीरे-धीरे बेहतर कैसे किया जा सकता है।
इस लेख में आप क्या सीखेंगे?
- Credit Score का मतलब
- CIBIL Score क्या है
- Score कैसे बनता है
- Loan पर क्या असर
- Score खराब क्यों होता
- Score कैसे Improve करें
- Credit Report कैसे Check करें
- Common Myths की सच्चाई
Credit Score क्या है?
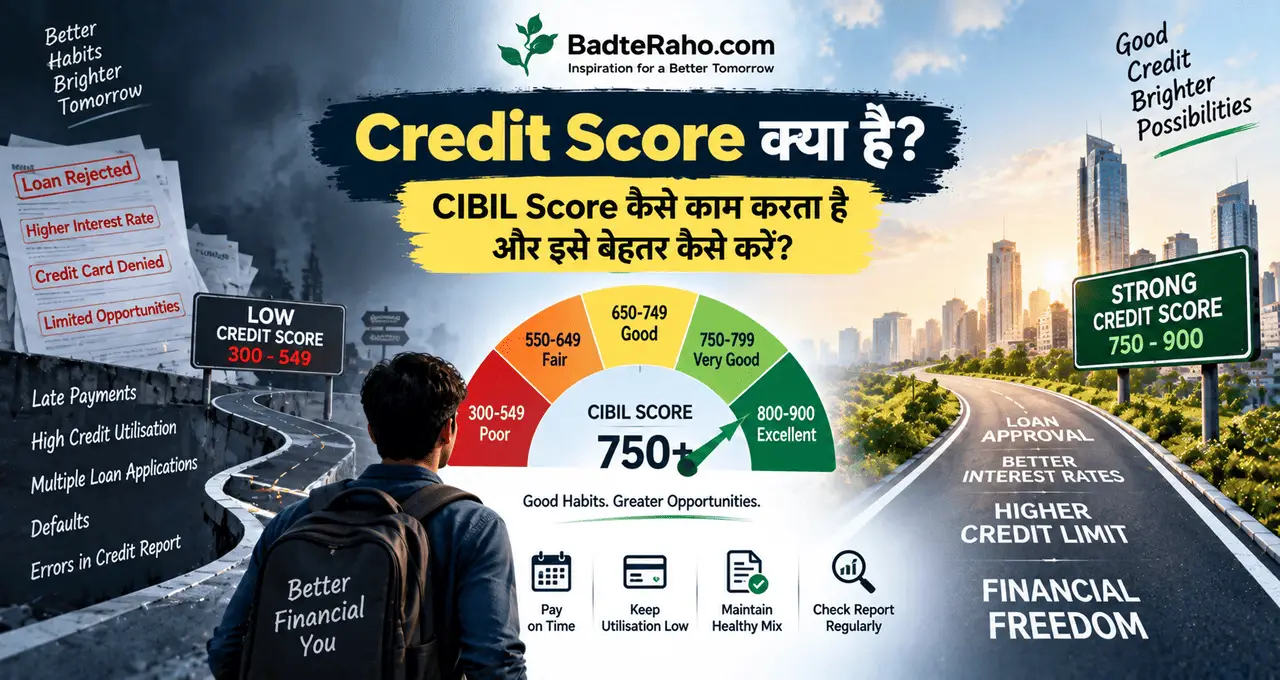
Credit Score एक numerical indicator है जो आपकी credit history के आधार पर यह दिखाने की कोशिश करता है कि आपने past में loans और credit accounts को किस तरह manage किया है।
India में commonly credit scores 300 से 900 की range में दिखाई देते हैं।
Generally score जितना higher होता है, credit profile उतनी stronger मानी जा सकती है।
लेकिन इसका मतलब यह नहीं कि:
900 score = loan guaranteed
या
कम score = loan कभी नहीं मिलेगा।
Loan approval में lender आपकी income, existing EMI, employment, age, loan type, repayment capacity और अपनी internal policy जैसी कई चीजें भी देख सकता है।
Credit Score सिर्फ़ उस decision का एक important हिस्सा है।
CIBIL Score क्या है?
CIBIL यानी TransUnion CIBIL India की credit information companies में से एक है।
यह banks और दूसरे lenders से reported credit information के आधार पर consumer credit reports और scores तैयार करता है।
लेकिन India में सिर्फ़ CIBIL ही credit bureau नहीं है।
दूसरे credit bureaus भी मौजूद हैं, इसलिए अलग-अलग bureaus से आपको थोड़ा अलग score दिखाई दे सकता है।
यही वजह है कि:
Credit Score = generic term
जबकि
CIBIL Score = TransUnion CIBIL द्वारा दिया गया credit score
फिर भी आम बोलचाल में “CIBIL Score” इतना popular हो चुका है कि लोग इसे पूरे credit score concept के लिए use कर देते हैं।
Credit Report और Credit Score में क्या फर्क है?
दोनों related हैं, लेकिन same नहीं।
Credit Report
यह आपकी credit history की detailed report होती है।
इसमें information हो सकती है:
- Active loans
- Closed loans
- Credit Cards
- Outstanding balances
- Repayment history
- Credit enquiries
- Reported defaults या delays
- Account status
Credit Score
Credit Report में मौजूद information के आधार पर बनाया गया numerical score होता है।
Simple example:
Credit Report = आपकी पूरी marksheet
Credit Score = overall performance का एक number
इसलिए अगर score अचानक गिरता है, तो सिर्फ़ number देखने के बजाय report में reason समझना ज्यादा useful है।
Credit Score कैसे बनता है?
Exact scoring formula credit bureaus का proprietary model होता है। इसलिए internet पर दिखाई देने वाले fixed percentages को universal formula मानना सही नहीं है।
लेकिन broadly कुछ factors important होते हैं।
1. Repayment History
आपने EMI और Credit Card bills समय पर pay किए या नहीं—यह बहुत important factor हो सकता है।
Repeated late payments या defaults आपकी credit profile को कमजोर कर सकते हैं।
अगर due date 5 तारीख है और आप regularly payment late करते हैं, तो सिर्फ़ “बाद में तो pay कर दिया” हमेशा enough नहीं होता।
Credit discipline का मतलब payment समय पर करना भी है।
2. Credit Utilisation
Credit Card में आपको एक limit मिलती है।
मान लीजिए limit ₹1 lakh है और आप हर month ₹95,000–₹1 lakh के आसपास use करते हैं।
अगर ऐसा regularly होता है, तो lender इसे high dependence on available credit के रूप में देख सकता है।
इसका मतलब Credit Card use करना खराब नहीं है।
Problem तब हो सकती है जब available limit का बहुत बड़ा हिस्सा लगातार इस्तेमाल हो रहा हो।
Better habit है card को spending extension की तरह नहीं, payment tool की तरह use करना।
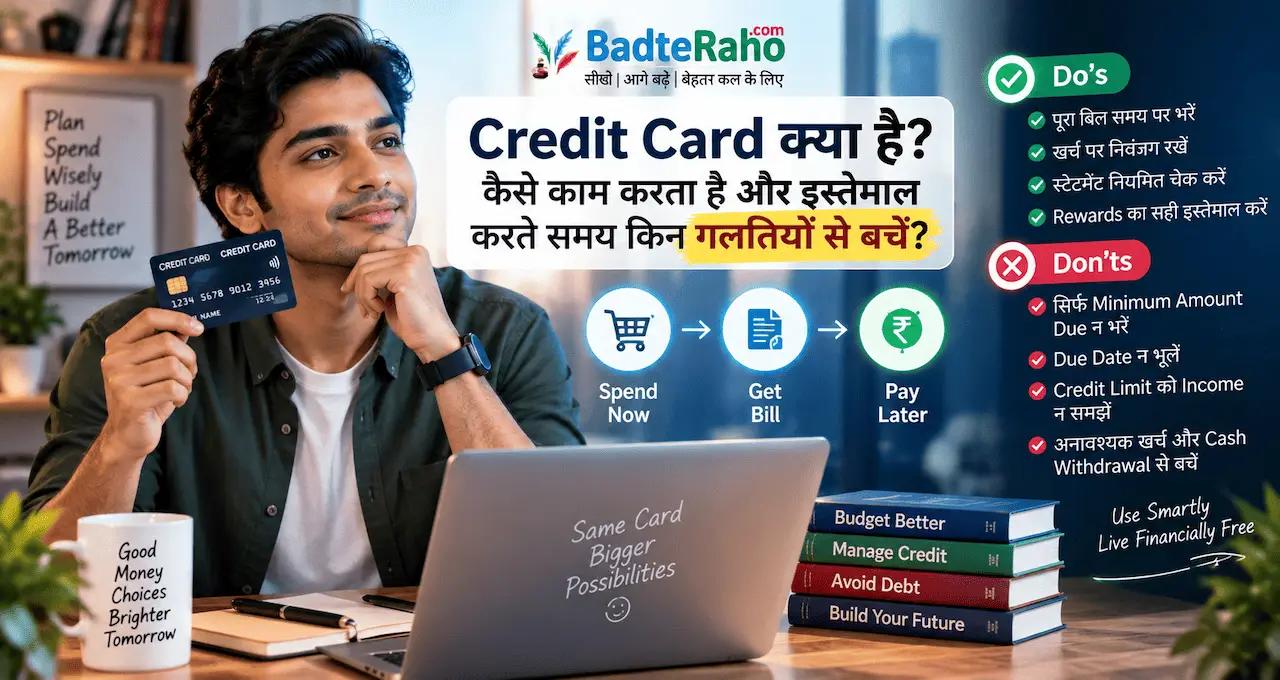
Credit Card की basic working clear नहीं है तो Credit Card क्या है? कैसे काम करता है और गलतियों से बचें पहले पढ़ सकते हैं।
3. Credit History की Age
अगर आपने कई वर्षों से credit responsibly manage किया है, तो lender के पास आपके behaviour की ज्यादा history available होती है।
इसीलिए पुराना well-managed credit account useful हो सकता है।
लेकिन सिर्फ़ score improve करने के लिए unnecessary account open रखना भी सही strategy नहीं।
Goal हमेशा healthy financial behaviour होना चाहिए, सिर्फ़ number manipulate करना नहीं।
4. Credit Mix
आपके credit profile में secured और unsecured credit का mix हो सकता है।
Secured loan का example home loan या vehicle loan हो सकता है जहाँ asset security से जुड़ा हो सकता है।
Credit Card और personal loan unsecured credit के examples हैं।
Balanced credit history useful हो सकती है, लेकिन इसका मतलब यह नहीं कि score improve करने के लिए अलग-अलग loans लेने चाहिए।
Loan सिर्फ़ Credit Score बनाने के लिए लेना खराब idea हो सकता है।
5. Credit Enquiries
जब आप loan या Credit Card के लिए apply करते हैं, lender आपकी credit report check कर सकता है।
इसे commonly hard enquiry से जोड़ा जाता है।
अगर बहुत कम समय में कई lenders के पास बार-बार applications की जाएँ, तो यह risk signal बन सकता है।
इसलिए सिर्फ़ “देखते हैं कौन approve करता है” सोचकर एक साथ कई Credit Cards या personal loans के लिए apply करना avoid करना बेहतर है।
अपना Credit Score Check करने से Score घटता है?
यह बहुत common myth है।
जब आप खुद अपना Credit Score या report check करते हैं, तो इसे generally self-check या soft enquiry के रूप में treat किया जाता है और इससे score को वैसा नुकसान नहीं होना चाहिए जैसा lender-initiated credit application enquiries से जुड़ सकता है।
इसलिए Credit Score check करने से डरने की जरूरत नहीं है।
Regularly report review करना actually useful habit हो सकती है क्योंकि इससे आपको errors या unknown accounts जल्दी दिखाई दे सकते हैं।
अच्छा CIBIL Score कितना माना जाता है?
आप अक्सर internet पर 750+ को strong score के रूप में देखेंगे।
Practical level पर higher score generally favourable माना जाता है, लेकिन किसी particular score पर loan approval की guarantee नहीं होती।
Lenders की policies अलग-अलग हो सकती हैं।
एक lender 740 score वाले applicant को approve कर सकता है, दूसरा नहीं।
क्यों?
क्योंकि lender सिर्फ़ score नहीं देख रहा है।
वह यह भी देख सकता है:
Monthly income.
Existing EMI.
Job stability.
Requested loan amount.
Loan-to-income burden.
Credit history.
Recent applications.
Internal risk rules.
इसलिए Credit Score को “loan पास कराने वाला magic number” समझना गलत है।
Credit Score खराब क्यों हो सकता है?
Score कमजोर होने के पीछे कई reasons हो सकते हैं।
EMI Late करना
Repeated delays negative signal बन सकते हैं।
Credit Card Bill Miss करना
Due payment ignore करना credit history को नुकसान पहुँचा सकता है।
बहुत ज्यादा Credit Use
Available limits routinely almost exhaust करना risk दिखा सकता है।
बार-बार Loan Apply करना
Short period में कई credit enquiries profile को weak दिखा सकती हैं।
Loan Settlement
Full repayment की जगह settlement credit report पर negative impression छोड़ सकता है।
Default
Loan repayment लंबे समय तक न करना ज्यादा serious issue हो सकता है।
Report में Error
कभी-कभी गलत account या incorrect status भी report में दिखाई दे सकता है।
इसीलिए score के साथ report देखना जरूरी है।
Credit Score कैसे बेहतर करें?
Credit Score overnight improve नहीं होता।
किसी app, agent या “30 दिन में 900 score” जैसी guarantee पर भरोसा न करें।
Better approach consistent financial habits हैं।
1. EMI समय पर Pay करें
Loan repayment को priority दें।
अगर भूलने की problem है तो reminders या auto-debit useful हो सकते हैं, लेकिन account में sufficient balance रखना भी जरूरी है।
2. Credit Card का Full Bill Pay करने की कोशिश करें
सिर्फ़ minimum due देखकर यह assume न करें कि आपका पूरा bill settle हो गया।
Remaining outstanding पर applicable interest और charges जारी रह सकते हैं।
अगर possible हो तो statement amount को due date तक पूरा pay करना healthier financial habit है।
3. Credit Limit को Salary मत समझें
₹2 lakh की Credit Card limit का मतलब यह नहीं कि आपकी income ₹2 lakh बढ़ गई।
Credit limit borrowed spending capacity है।
Personal finance मजबूत रखने के लिए Personal Finance क्या है? कमाई, खर्च, बचत और Investment Manage करने का सही तरीका useful foundation है।
4. एक साथ कई Loans के लिए Apply न करें
अगर loan की genuine जरूरत है, तो पहले eligibility और repayment capacity समझें।
फिर relevant lenders से compare करें।
Randomly 8–10 applications करना अच्छी strategy नहीं है।
हर approval offer आपके लिए affordable होना जरूरी नहीं है।
5. Old Credit Accounts सोच-समझकर Close करें
Old Credit Card बंद करने से पहले देखें कि वह आपके overall credit profile और available limit पर क्या असर डाल सकता है।
अगर card पर unnecessary annual fee है या misuse का risk है तो बंद करना sensible हो सकता है।
लेकिन सिर्फ़ “मैं use नहीं करता” reason से हर पुराना account तुरंत close करना जरूरी नहीं है।
Decision financial need के हिसाब से लें।
6. Credit Report में Errors Check करें
मान लीजिए आपने loan पूरा चुका दिया, लेकिन report में अभी भी overdue दिखाई दे रहा है।
या किसी unknown loan account का entry दिख रहा है।
ऐसी situation में ignore न करें।
Relevant lender और credit bureau के dispute process के जरिए correction request की जा सकती है।
Useful details save रखें:
Account number.
Payment receipts.
Closure documents.
No-dues certificate जहाँ available हो.
Correspondence.
Credit Report सिर्फ़ loan लेने से पहले नहीं, समय-समय पर review करना useful है।
“No Credit History” भी Problem हो सकती है?
अगर आपने कभी loan या Credit Card use नहीं किया, तो आपके पास पर्याप्त credit history नहीं हो सकती।
इस situation में report पर traditional score की जगह insufficient history से जुड़ी indication दिखाई दे सकती है।
इसका मतलब यह नहीं कि आपका financial behaviour खराब है।
बस lender के पास आपकी past borrowing behaviour judge करने के लिए कम information है।
अगर आपको credit की जरूरत ही नहीं है तो सिर्फ़ score बनाने के लिए loan लेना जरूरी नहीं है।
लेकिन future में Credit Card लेते हैं, तो उसे responsibly use करके history gradually build की जा सकती है।
Credit Score कितने समय में Improve होता है?
इसका fixed answer नहीं है।
अगर सिर्फ़ छोटी reporting issue correct हुई है तो change relatively जल्दी दिखाई दे सकता है।
अगर history में multiple missed payments या serious defaults हैं, तो improvement में ज्यादा समय लग सकता है।
Credit bureaus lenders द्वारा report की गई information पर depend करते हैं, इसलिए account changes update होने में भी कुछ समय लग सकता है।
Simple rule:
Credit Score repair कोई instant hack नहीं, behaviour + time का combination है।
Repeated good repayment history gradually stronger profile बना सकती है।
Loan जल्दी चुकाने से Credit Score हमेशा बढ़ता है?
जरूरी नहीं कि हर loan prepayment से score automatically jump करे।
Loan जल्दी खत्म करना financial point of view से useful हो सकता है अगर इससे interest बचता है और terms suitable हैं।
लेकिन Credit Score सिर्फ़ एक action पर depend नहीं करता।
पूरी credit history important होती है।
इसलिए loan repayment decision सिर्फ़ score देखकर नहीं करें।
Interest cost, prepayment charges, emergency savings और बाकी financial goals भी देखें।
Emergency savings की planning के लिए Emergency Fund क्या है? कितना पैसा बचाकर रखना चाहिए और इसे कैसे बनाएं? useful रहेगा।
Credit Score के 6 Common Myths
“High Salary मतलब High Credit Score”
जरूरी नहीं।
Income और Credit Score अलग concepts हैं।
“Credit Card Use न करना ही Best है”
Responsible use credit history build करने में मदद कर सकता है।
“Minimum Due भर दिया तो Bill खत्म”
जरूरी नहीं।
“अपना Score Check करने से Score घटता है”
Self-check generally उसी तरह harmful enquiry नहीं होती।
“750 Score है तो Loan Guaranteed”
Approval lender की बाकी conditions पर भी depend करता है।
“किसी Agent को पैसे देकर Score तुरंत बढ़ाया जा सकता है”
Genuine negative history को magically delete करने का shortcut नहीं होता।
Loan लेने से पहले सिर्फ़ Credit Score मत देखें
मान लीजिए आपका score अच्छा है और bank ₹8 lakh personal loan offer कर रहा है।
इसका मतलब यह नहीं कि आपको loan लेना ही चाहिए।
पहले देखें:
EMI comfortably pay कर पाएँगे?
Emergency Fund बचा रहेगा?
Existing loans कितने हैं?
Loan किस purpose के लिए है?
Total interest कितना होगा?
Monthly budget disturb तो नहीं होगा?
एक अच्छा Credit Score borrowing आसान कर सकता है।
लेकिन अच्छा financial decision वही है जिसमें loan affordable भी हो।
Monthly cash flow समझने के लिए Monthly Budget कैसे बनाएं? Income, Expenses, Savings और Financial Goals Manage करने की Practical Guide useful रहेगा।
अपना Credit Health Check कैसे करें?
हर कुछ समय बाद 10-minute review कर सकते हैं।
देखें:
Credit Score roughly कहाँ है?
Report में सभी accounts आपके हैं?
कोई payment overdue दिख रही है?
Closed loan properly updated है?
Credit Card balance unusually high तो नहीं?
Unknown enquiry दिखाई दे रही है?
किसी account में error है?
अगर सब सही है, तो score को रोज़ check करने की ज़रूरत नहीं है।
Credit Score को fitness tracker की तरह समझें।
Number useful है, लेकिन real goal healthy habits हैं।
आज से क्या करें?
अगर आपने कभी Credit Report नहीं देखी है, तो पहला step कोई नया loan लेना नहीं होना चाहिए।
पहले अपनी report देखें।
फिर तीन चीजें check करें:
Payment History: कोई overdue या missed payment?
Accounts: सभी loans और cards आपके हैं?
Balances: Outstanding सही दिखाई दे रहा है?
अगर error है तो correction process शुरू करें।
अगर सब सही है लेकिन score weak है, तो shortcut ढूंढने के बजाय अगले कुछ months disciplined repayment पर focus करें।
Credit profile धीरे बनती है और धीरे repair भी होती है।
आख़िर में एक छोटी सी बात
Credit Score को लेकर दो extremes common हैं।
कुछ लोग इसे completely ignore करते हैं।
दूसरे हर कुछ दिनों में score check करके परेशान रहते हैं।
दोनों की जरूरत नहीं।
Credit Score को बस अपनी credit habits की report card की तरह देखें।
EMI समय पर भरें।
Credit Card bills responsibly manage करें।
Available credit को unnecessarily max out न करें।
हर offer पर नया loan apply न करें।
और Credit Report में errors समय पर check करें।
अगर ये habits strong हैं, तो score को अलग से “manage” करने की जरूरत काफी कम हो जाती है।
सबसे important बात—अच्छा Credit Score financial health का एक हिस्सा है, पूरी financial health नहीं।
आपके लिए Credit Score में सबसे ज्यादा confusion किस बात को लेकर है—750 का target, Credit Card usage, loan enquiries, old defaults या Credit Report errors? अपनी राय, experience, feedback या सवाल comment में जरूर share करें।